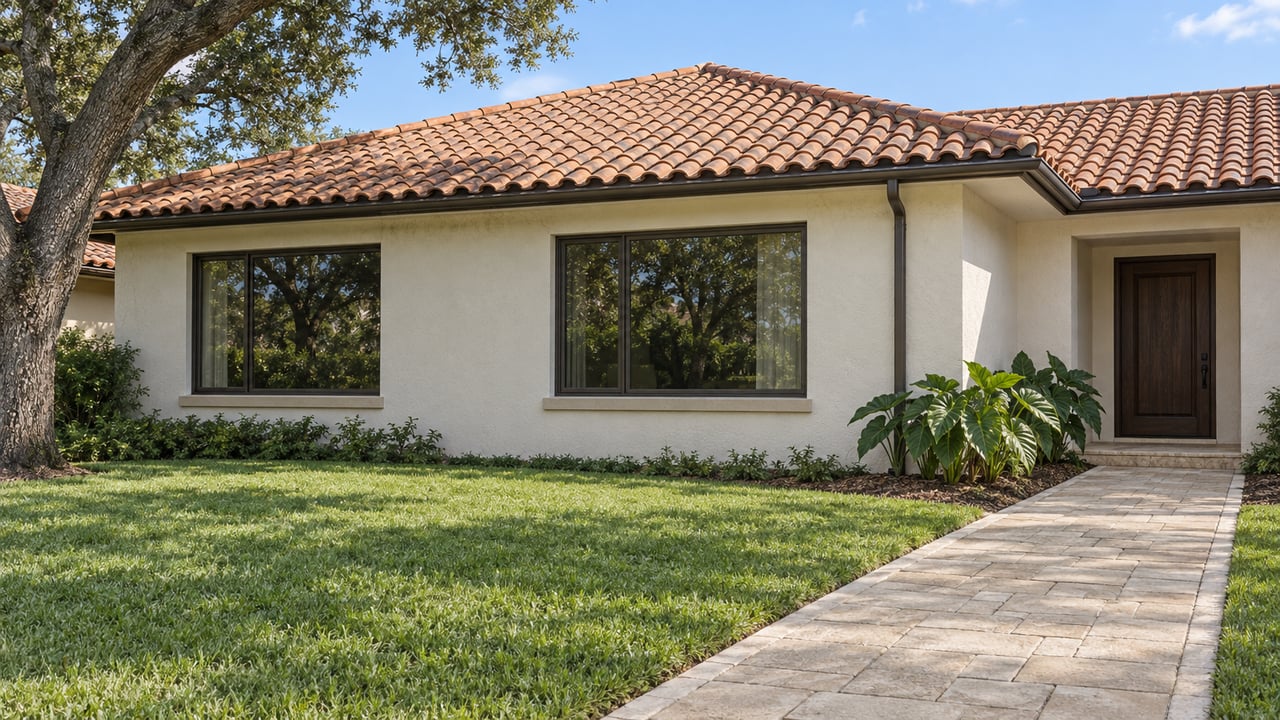
Every home in The Lakes of Parkland comes from one short building window. The community's homeowners association describes Lakes at Parkland as 116 single-family homes built between 1995 and 1998, set west of State Road 7, north of NW 74th Place, and east of Mill Run. That window falls after Hurricane Andrew and before Florida adopted its first statewide building code. Because of that timing, a buyer's insurance quote here depends on paperwork from three decades ago and on the roof features an inspector can see today, more than on the year built.
This shows up during the contract period, when the buyer's agent is collecting quotes and the inspection reports start arriving. Here is how the pieces fit together for a home from this era.
The Checkbox That Asks for a Date
Florida's Uniform Mitigation Verification Inspection Form, OIR-B1-1802, is the wind mitigation report insurers use to apply discounts. Question 1 asks which building code was in force when the home's original permit application was filed. Homes in the High-Velocity Hurricane Zone, which the form defines as Miami-Dade and Broward counties, get an extra option. The form reads:
"For the HVHZ Only: Code in force at time of permit application was the SFBC-94: Year Built ______. For homes built in 1994, 1995, and 1996, provide a permit application with a date after 9/1/1994."
So for a Lakes at Parkland home finished in 1995 or 1996, the year built doesn't settle the answer. The inspector needs a permit application dated after September 1, 1994. If that document can't be produced, or the home doesn't meet the requirements of any listed code, the form falls back to option D, "Unknown."
The dates involved are close together. A federal notice records that Dade County adopted the ASCE wind-load provisions into the South Florida Building Code effective January 1, 1994. The form's cutoff is September 1, 1994, a different date tied to permit applications. The statewide Florida Building Code took effect March 1, 2002, years after the last home here was finished. The form's two Florida Building Code options, "FBC 2001 & 2004" and "FBC 2007 and later," describe homes permitted after that change. That puts the whole community in the SFBC-94 question or nowhere.
What the Code Box Does Not Prove
Even with the SFBC-94 box checked, the rest of the form still checks the house one feature at a time. Being permitted under the post-Andrew code doesn't show that a particular home has clips, wraps, a sealed deck, or impact protection. Each of those gets verified separately. The inspector grades four structural items:
- Roof deck attachment, ranked from a lower fastening tier up to tighter 8d nail spacing and stronger or engineered systems.
- Roof-to-wall attachment, classified as toenails, clips, single wraps, or double wraps, each with defined connection details and uplift-capacity thresholds.
- Secondary water resistance, meaning a sealed roof deck installed by a qualifying method. The form specifically excludes standard underlayment or hot-mopped felt on their own.
- Opening protection, covering wall and roof openings, scored by impact and cyclic-pressure levels, with separate categories for unverified or no protection.
Two items are rated by the weakest link. Roof-to-wall attachment goes by the weakest connection the inspector finds, and opening protection goes by the weakest protected opening. In a community where the HOA describes most homes as having pools and waterfront views, sliding doors and wide glass are common. A house with impact windows on the front and one unprotected rear slider can therefore score at the slider's level. Two houses on the same street, built the same year, can come back with very different reports.
April 2026 Changed Which Reports Still Count
Sellers who had a wind mitigation inspection a few years ago often expect to hand that report to the buyer. This year that may not work. The Florida Office of Insurance Regulation revised the form to OIR-B1-1802 Rev. 04/26, and Citizens Property Insurance announced in a March 19, 2026 bulletin that inspections on or after April 1, 2026 must use the new version.
Citizens' bulletin sets out when it will still accept the earlier Rev. 01/12 form. The structure must be unchanged, and the report must have been completed within five years before April 1, 2026. A report from before April 2021 doesn't meet that test. Neither does one from any year if the house has since had a new roof or new windows. On homes from 1995 to 1998, roofs and openings are often the most likely things to have been changed since the last report.
Every House Here Is Past the 4-Point Line
Alongside the wind form, a second inspection looks at the home's systems. Citizens requires a 4-point inspection on homeowners, dwelling, and mobile-home applications when the property is more than 20 years old. Every home in a community finished by 1998 is past that mark in 2026.
The Citizens 4-point form records roof age and condition, the electrical system and any hazards, HVAC age and operation, plumbing age and materials, and any leaks. Its instructions require details on anything that isn't in good working order. Plumbing material matters most at this age. Citizens states that new-business homes over 20 years old with polybutylene piping aren't insurable on its listed homeowners and dwelling forms.
Private carriers set their own rules. Florida's Insurance Consumer Advocate says 4-point criteria vary by insurer and describes a review of system age, type, condition, and safety, not a single statewide age cutoff. The same report can be fine with one carrier and trigger questions with another.
The Roof Is Measured From Its Last Full Replacement
On a home built in the late 1990s, the roof is often newer than the rest of the house, and Florida law has detailed rules for counting its age. Under Florida Statutes section 627.7011, an insurer can't deny or nonrenew a homeowners policy solely because the roof is less than 15 years old. For roofs 15 years or older, the statute requires that an authorized inspection be allowed before replacement can be required. If the inspector finds at least five years of remaining useful life, the insurer can't refuse coverage on age alone. Age counts from the last date the entire roof surface was built or replaced to code. For a roof replaced in stages, it counts from when the partial replacements began that together covered 100 percent.
How the roof was last replaced also affects future repairs. Under section 553.844, when a roof system was built, repaired, or replaced to the 2007 Florida Building Code or later, repairing 25 percent or more of it requires only the repaired portion to meet current code. An original SFBC-94 roof doesn't qualify for that exception. A replacement roof installed under the 2007 code or later does. A 2026 bill, SB 808, would have changed the roof-age provisions. The Senate records it as having died in committee on March 13, 2026, so the 15-year and five-year framework remains in place.
Where the Paper Trail Lives
Every section above depends on documents, and for a Parkland home they're spread across several offices.
| Record | Where it sits | What to know |
|---|---|---|
| Original permit and roof permits | City of Parkland Building Division, 954.753.5447 | The city's FAQ says permit information is searchable in the city's system by address, owner, or contractor but is not online. Re-roofing requires a permit. |
| Recorded subdivision plat | City of Parkland document repository; Broward County Official Records | The city's repository has a Lakes at Parkland folder with a final recorded plat entry. County records say plats are searchable regardless of recording date. |
| Permit application status for new work | Broward County ePermits OneStop | Built for submitting and tracking applications, not described as a historical archive. |
The details are on the Parkland Building Division FAQ and the Broward County Official Records search. For a 1995 or 1996 home, the original permit application date is what the wind form's SFBC-94 option asks for. Roof permit records show when the current roof's age clock started.
Why the Documents Matter More as Rates Fall
Florida's insurance market looks better than it did a few years ago, which puts more weight on these documents. Citizens reported 266,231 policies in force as of August 31, 2026, compared with 1,407,805 as of September 30, 2023. In December 2025, Citizens said 17 new insurers had entered Florida since the state's reforms and that its 2025 depopulation program moved more than 546,000 policies to private companies.
Rate filings have also turned. The Office of Insurance Regulation's September 22, 2026 update put the 30-day average homeowners rate request at -4.8 percent and the 180-day average at -0.3 percent. It also reported that 48 companies had filed decreases since January 2024. The governor's office reported that Citizens' approved 2026 rates averaged an 8.7 percent statewide decrease and a 14.1 percent reduction for about 27,000 Broward homes.
These are averages, and a falling average doesn't guarantee a lower premium for any one house. With more carriers competing for business, though, a Lakes at Parkland home's quote depends more on what its file shows. That includes the permit date, the weakest opening, the roof's last full replacement, and the plumbing material on the 4-point report.
Frequently Asked Questions
Does a 1997 or 1998 home here need the September 1994 permit date? The form asks for the permit application date only for homes built in 1994, 1995, and 1996. For other years in the SFBC-94 option, it asks for the year built.
Is a 2022 wind mitigation report still usable? For Citizens, a Rev. 01/12 report is accepted if it was completed within five years before April 1, 2026 and the structure hasn't changed. Other carriers set their own rules.
Do private insurers use the same 4-point age trigger as Citizens? Not necessarily. Florida's Insurance Consumer Advocate says criteria vary by insurer.
If you're preparing to sell or buy in The Lakes of Parkland, we can help you collect the permit history, roof records, and current inspection reports before the contract clock starts, so the insurance review runs on documents you've already seen. Bill Sohl is a licensed general contractor, and his team knows how homes from this building era were put together. Bill Sohl Luxury Homes Team is ready when you are. Contact Us.
This article is general information, not legal, tax or financial advice. Consult a qualified professional about your situation.